If you want to pay off your mortgage faster, even shaving a few years off your repayment schedule can reduce the amount of interest you pay, increase your home equity faster, and give you greater financial flexibility later in life.
But there is no single strategy that works for every Canadian homeowner.
Your mortgage rate, remaining amortization, lender rules, household budget, other debts, and future plans all matter. Before making a large extra payment, it is especially important to understand your mortgage’s prepayment privileges, because exceeding them can trigger a penalty.
At Kiani & Co., we believe homeownership should support both your lifestyle and your longer-term financial goals. Led by Sarah Kiani, Realtor, our team helps homeowners across Burlington, Oakville, Hamilton, and surrounding communities make informed real estate decisions at every stage of ownership.
If one of your goals is to pay off your mortgage faster, these eight strategies are a good place to start.
This article provides general real estate and mortgage information and is not personalized financial advice. Mortgage terms vary by lender and contract. Speak with your lender, mortgage broker, or qualified financial professional before making changes to your mortgage.
1. Increase Your Regular Mortgage Payments
One of the simplest ways to pay down a mortgage faster is to increase the amount of each regular payment.
Even a relatively modest increase means more money is being directed toward your mortgage over the course of the year.
The Financial Consumer Agency of Canada notes that mortgage contracts may allow borrowers to increase their regular payments as part of their prepayment privileges. The exact amount you are allowed to increase can vary by lender and mortgage contract.
Before increasing your payment, check:
- How much your lender allows you to increase it
- How often you can change your payment
- Whether the increase can later be reversed
- Whether exceeding the permitted amount could trigger a penalty
Some lenders may not allow you to lower an increased payment again until the end of the mortgage term, so make sure the higher payment is sustainable within your household budget.
You can review the Government of Canada’s guidance on paying off your mortgage faster before making changes.
2. Make Lump-Sum Payments When You Have Extra Cash
A lump-sum payment is an additional payment made directly against your mortgage balance on top of your normal scheduled payments.
Depending on your lender and mortgage contract, you may be able to make lump-sum payments at specific times or up to a certain percentage of the mortgage amount each year.
Possible sources for a lump-sum payment might include:
- A work bonus
- Tax refund
- Inheritance
- Sale of another asset
- Savings accumulated beyond your emergency needs
- Additional business or employment income
The benefit is straightforward. Reducing the principal earlier means there is less mortgage balance on which future interest can accumulate.
However, homeowners should never assume they can make an unlimited extra payment.
With a closed mortgage, there is usually a limit on how much additional principal you can repay each year without incurring a prepayment penalty. Prepayment privileges vary from lender to lender. You can review the Government of Canada’s guidance on choosing a mortgage and comparing mortgage features.
Check your mortgage agreement or contact your lender before transferring a large amount.
3. Switch to Accelerated Biweekly or Weekly Payments
Changing the frequency of your mortgage payment can also help you pay the balance down more quickly.
The important distinction is between a standard biweekly payment and an accelerated biweekly payment.
With an accelerated payment schedule, you effectively make the equivalent of one additional monthly mortgage payment each year.
According to the Financial Consumer Agency of Canada, accelerated weekly or biweekly payments can reduce interest costs and help you pay off your mortgage faster.
For homeowners who are paid every two weeks, accelerated biweekly payments can also fit naturally with their cash-flow schedule.
Before switching, ask your lender to show you:
- Your new payment amount
- Your projected amortization
- Your estimated interest savings
- Whether there are any restrictions associated with changing payment frequency
The goal is not simply to pay more frequently. The advantage comes from increasing the total amount that goes toward the mortgage over the year.
4. Use Your Full Prepayment Privilege When It Makes Sense
Many Canadian mortgages include some form of annual prepayment privilege.
For example, a mortgage contract might allow the borrower to:
- Increase regular payments by a specified percentage
- Make an annual lump-sum payment
- Make additional payments on certain dates
The permitted amount varies significantly between mortgage products.
This is why two homeowners with mortgages from different lenders may have very different options even if their balances and interest rates are similar.
If paying off your mortgage quickly is important to you, prepayment flexibility should also be considered when choosing a mortgage, not just the advertised interest rate.
The lowest rate is not automatically the best mortgage if another product gives you significantly more flexibility to reduce your principal without penalties.
Federally regulated lenders are required to provide information about applicable mortgage prepayment privileges and penalties.
5. Put Raises and Extra Income Toward the Mortgage
One reason increasing mortgage payments can feel difficult is that homeowners become accustomed to their existing monthly budget.
A practical alternative is to increase your mortgage payment when your income increases.
For example, if you receive a raise, you might direct a portion of that increase toward your mortgage instead of immediately increasing your lifestyle spending by the same amount.
This can work particularly well because your household budget was already functioning before the raise.
The same idea can apply to recurring additional income.
The key is sustainability.
You do not necessarily have to direct every extra dollar toward the mortgage. A consistent, manageable increase maintained for years can be more useful than an aggressive payment increase that leaves your household short on cash and eventually has to be reversed.
6. Keep Your Payment the Same If Your Rate Drops at Renewal
Mortgage renewal can create another opportunity to reduce your amortization.
If you renew at a lower interest rate, your required mortgage payment may decrease.
Instead of immediately lowering your payment, you may be able to keep paying approximately what you were paying before.
More of that payment can then go toward principal, helping you reduce the mortgage faster.
The Financial Consumer Agency of Canada specifically identifies maintaining your existing payment after obtaining a lower rate as one strategy for accelerating mortgage repayment.
Renewal is also a good time to compare:
- Interest rates
- Prepayment privileges
- Payment flexibility
- Penalty calculations
- Portability
- Term length
- Remaining amortization
You are generally not required to renew with your existing lender. Shopping around can help you evaluate whether another mortgage provides terms that better suit your goals. The Government of Canada provides more information on renewing your mortgage.
7. Avoid Extending Your Amortization Without Considering the Long-Term Cost
Extending your amortization can reduce your required monthly payment, which may be useful when affordability is the priority.
But if your goal is to pay off your mortgage faster, extending the amortization generally moves you in the opposite direction.
A longer amortization means it takes longer to repay the mortgage and generally results in more total interest being paid.
The Financial Consumer Agency of Canada explains the relationship between mortgage term, amortization, payments, and total borrowing costs in its guidance on mortgage terms and amortization.
That does not mean extending an amortization is always a bad decision.
There may be situations where lowering monthly payments is necessary or strategically appropriate.
The important point is to understand the tradeoff between short-term monthly affordability and long-term borrowing costs.
8. Review Your Mortgage Strategy Before Making a Move
Paying down your mortgage aggressively makes sense for some homeowners, but your plans for the property matter.
If you expect to move soon, you should understand what happens to your mortgage when the home is sold.
Breaking a closed mortgage before the end of its term can result in a prepayment penalty. Depending on the mortgage and lender, the penalty can be substantial.
Your mortgage may also be portable, which could allow you to transfer some or all of the existing mortgage to another property.
If moving is already on your radar, read our guide on how to keep your low mortgage rate when moving before making a large mortgage change.
Understanding your future real estate plans before restructuring or aggressively prepaying your mortgage can help you avoid unnecessary penalties and preserve valuable mortgage features.
Should You Pay Off Your Mortgage as Fast as Possible?
Becoming mortgage-free is an attractive goal, but the fastest possible repayment schedule is not automatically the right financial strategy for every household.
Before directing all available cash toward the mortgage, consider the rest of your financial picture.
You may also need funds for:
- An emergency reserve
- Higher-interest debt
- Retirement savings
- Home maintenance and repairs
- Children’s education
- Upcoming major expenses
- Other investments
For example, paying additional principal on a mortgage while carrying much more expensive credit-card debt may not be the best use of available cash.
Liquidity matters too.
Once money has been used to reduce your mortgage principal, accessing that equity again may require borrowing against your home, refinancing, or using another credit product, potentially at additional cost.
The right goal is not necessarily to eliminate the mortgage at any cost. It is to build a repayment strategy that supports your overall financial position.
Open vs. Closed Mortgages Matter
Your ability to make extra mortgage payments is heavily influenced by whether your mortgage is open or closed.
Open Mortgages
An open mortgage generally allows you to make additional payments or repay the entire mortgage without a prepayment penalty.
That flexibility can be valuable for someone who expects to:
- Sell soon
- Receive a significant amount of cash
- Pay off the mortgage early
- Make unusually large additional payments
However, open mortgages may come with a higher interest rate than comparable closed mortgages.
Closed Mortgages
Closed mortgages often offer lower rates but place limits on how much principal can be prepaid during the term without penalty.
Many closed mortgages still include valuable prepayment privileges.
The important step is understanding exactly what your own contract allows rather than relying on a general rule.
FCAC recommends reviewing these privileges carefully when choosing a mortgage.
Be Careful About Prepayment Penalties
Paying down debt faster sounds straightforward, but exceeding your contractual prepayment privilege can become expensive.
A lender may charge a prepayment penalty if you:
- Pay more than your mortgage allows
- Break your mortgage before the term ends
- Transfer the mortgage to another lender before maturity
- Repay the entire mortgage early
These penalties can reach thousands of dollars depending on the mortgage and circumstances. The Government of Canada provides guidance on understanding and reducing mortgage prepayment penalties.
Before making a large payment, ask your lender for the exact amount you are currently permitted to prepay without penalty.
If you are considering breaking or refinancing the mortgage, ask for a written estimate of the applicable penalty as well.
Mortgage Renewal Is a Good Time to Reassess Your Plan
Do not treat your mortgage renewal notice as something that simply needs a signature.
Renewal is an opportunity to reassess your overall mortgage strategy.
Ask yourself:
- Is becoming mortgage-free sooner still a priority?
- Can I comfortably increase my payment?
- Do I expect to move during the next term?
- Do I need more prepayment flexibility?
- Is my current lender still competitive?
- Should I shorten my remaining amortization?
- How would a different term affect my plans?
If your mortgage is with a federally regulated financial institution, your lender generally must provide your renewal statement at least 21 days before the end of your current term.
Starting your research well before that date gives you more time to compare options rather than accepting the first renewal offer presented.
Paying Down Your Mortgage and Building Home Equity
Every mortgage payment that reduces your principal increases your ownership stake in the property, although your total home equity also depends on the home’s market value.
Accelerating that process can give homeowners greater flexibility over time.
More equity may become useful when you eventually:
- Sell and move to another home
- Downsize
- Purchase an investment property
- Renovate
- Help fund another major financial goal
But your home is still only one part of your financial picture.
Kiani & Co.’s approach is to help clients make real estate decisions in the context of where they want to be next, not just where they are today.
If your long-term goals include moving, investing, or building wealth through property ownership, you may also want to read our guide on building wealth through real estate.
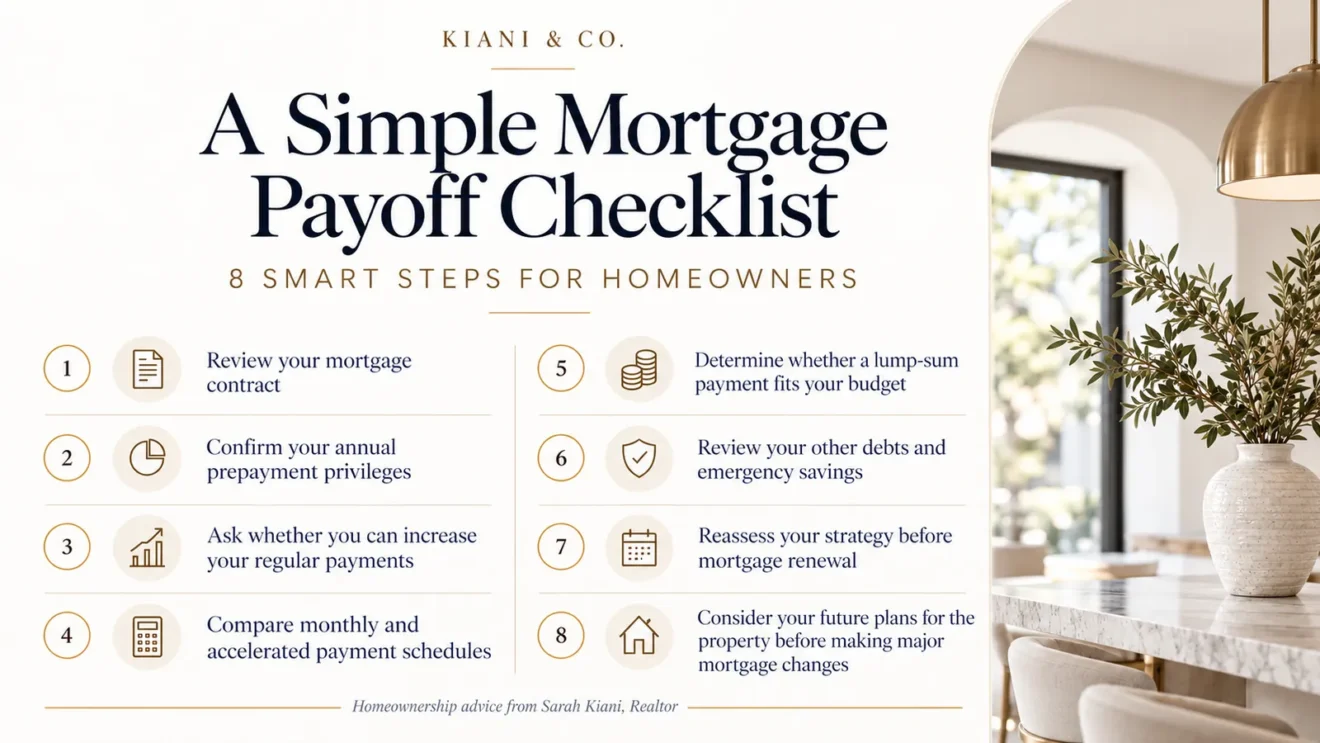
A Simple Mortgage Payoff Checklist
If you want to start paying off your mortgage faster, begin with these steps:
- Review your mortgage contract.
- Confirm your annual prepayment privileges.
- Ask whether you can increase your regular payments.
- Compare monthly and accelerated payment schedules.
- Determine whether a lump-sum payment fits your budget.
- Review your other debts and emergency savings.
- Reassess your strategy before mortgage renewal.
- Consider your future plans for the property before making major mortgage changes.
You can also use the Government of Canada’s mortgage resources and calculators to compare different repayment scenarios.
Planning Your Next Move With Kiani & Co.
Paying off your mortgage faster can strengthen your equity position and reduce long-term borrowing costs, but your mortgage strategy should also fit your broader real estate plans.
You may eventually want to upsize, downsize, relocate, purchase an investment property, or use the equity you have built to support another goal.
That is where real estate planning and mortgage planning begin to overlap.
Kiani & Co. helps homeowners understand the real estate side of those decisions, including current property value, market conditions, neighbourhood opportunities, and the potential timing of a future purchase or sale.
If you are considering your next move in Burlington, Oakville, Hamilton, Mississauga, Ancaster, Grimsby, Toronto, or the surrounding GTHA, contact Kiani & Co. to start the conversation.
Frequently Asked Questions About Paying Off a Mortgage Faster in Canada
What is the fastest way to pay off a mortgage in Canada?
There is no single fastest strategy that works for everyone. Common approaches include increasing regular payments, making lump-sum prepayments, choosing accelerated weekly or biweekly payments, and keeping payments higher when renewing at a lower interest rate.
Can I make extra mortgage payments in Canada?
Often, yes, but the amount and timing depend on your mortgage contract. Closed mortgages commonly have specific prepayment privileges, while open mortgages generally allow greater repayment flexibility.
What happens if I exceed my mortgage prepayment limit?
Your lender may charge a prepayment penalty if you pay more than your mortgage contract permits during the term. Confirm your available privilege before making a large additional payment.
Are accelerated biweekly payments worth it?
They can help homeowners pay down a mortgage faster because an accelerated schedule generally results in the equivalent of an extra monthly payment each year. Whether it is appropriate for you depends on your budget and mortgage terms.
Should I use a tax refund to pay down my mortgage?
A tax refund can potentially be used for a lump-sum mortgage payment if your mortgage allows it. Before doing so, consider your emergency savings, other debts, upcoming expenses, and overall financial priorities.
Should I shorten my amortization when I renew?
A shorter amortization can help you repay the mortgage faster and reduce total interest, but it generally increases your required payments. Make sure the payment remains comfortable within your budget.
Can I pay my mortgage off completely before the term ends?
You may be able to, but a closed mortgage can impose a prepayment penalty for paying the full balance before the end of the term. Open mortgages generally provide more flexibility. Check with your lender first.
Is paying off my mortgage better than investing?
That depends on factors including your mortgage rate, investment goals, risk tolerance, tax situation, other debts, and need for accessible savings. This is a broader financial-planning decision, so personalized advice from a qualified financial professional may be appropriate.
What happens to my mortgage if I sell my home before it is paid off?
The mortgage is typically repaid from the sale proceeds at closing unless an arrangement such as mortgage portability applies. Paying off a closed mortgage before the end of its term may trigger a prepayment penalty.